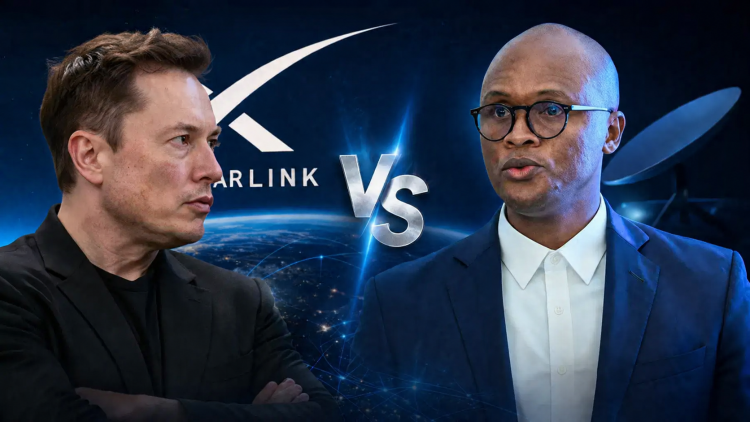
The rapid scaling of low Earth orbit (LEO) satellite internet across Africa has reached a fascinating geopolitical paradox. With its official activation in Côte d’Ivoire, SpaceX’s Starlink has successfully turned on high-speed, low-latency connectivity across 27 distinct African markets.
Yet, the continent’s most industrialized economy—and the birthplace of Elon Musk—remains completely dark. South Africa continues to be locked out of the global satellite rollout, caught in a complex web of equity-ownership laws, static regulatory frameworks, and intensifying commercial competition.
The African Footprint: A Velocity Comparison
Starlink’s growth trajectory across Sub-Saharan Africa has bypassed traditional telecom infrastructure limitations, scaling up user numbers faster than legacy fixed-line deployments could ever dream of.
Deconstructing the South African Regulatory Impasse
The barrier preventing Starlink from setting up a local entity isn’t a lack of market demand, but rather a deeply entrenched regulatory architecture designed around domestic equity transformation.
The regulatory logjam is driven by three distinct structural hurdles:
-
BEE Equity Mandates: The Electronic Communications Act mandates that any holder of a national telecommunications license must feature a minimum of 30% equity ownership held by historically disadvantaged groups (HDGs). SpaceX’s global operating model heavily resists carving out localized equity stakes.
-
The 17-Year Licensing Freeze: ICASA has not issued a brand-new, individual Electronic Communications Network Services (ECNS) license in 17 years. For Starlink to enter, it cannot simply apply for a new slot; it must buy an existing license from a local holder and navigate an intricate regulatory transfer process.
-
Policy Flexibility Debate: Communications Minister Solly Malatsi is reviewing public submissions on a policy framework that might allow global satellite firms to substitute direct equity transfers with targeted local social investments. However, this policy is far from finalized.
The Competitive Vacuum: Who Steps into the Gap?
While Starlink remains locked out officially, the South African market isn’t waiting. A dual-track counter-movement is unfolding across consumer behavior and corporate strategy:
1. The Roaming Grey Market
Desperate for reliable off-grid connectivity, thousands of South African consumers and rural businesses are actively exploiting a regulatory loophole. They purchase Starlink hardware via certified distributors in officially supported neighboring countries (like Mozambique or Botswana) and operate them within South African borders utilizing Starlink’s global or regional roaming features.
2. The Institutional Alternatives
Starlink’s regulatory hesitation has opened the door wide for competitors willing to play within local framework guidelines:
| Competitor / Platform | Strategic Approach | Local Market Positioning |
| Amazon Project Kuiper | Local Provider Partnership | Entering the market via a direct strategic distribution deal with Herotel, bypassing equity hurdles through localized infrastructure channels. |
| Vodacom & MTN | Hybrid Satellite-Cellular | Deploying direct-to-cell satellite integrations to augment their existing terrestrial networks without requiring dedicated user terminals. |
The Operational Reality: The South African impasse proves that raw technological superiority cannot entirely bypass sovereign regulatory structures. If the Ministry of Communications fails to establish an alternative compliance pathway for global satellite providers, South Africa risks falling behind its continental peers in the race for total rural digital inclusion.