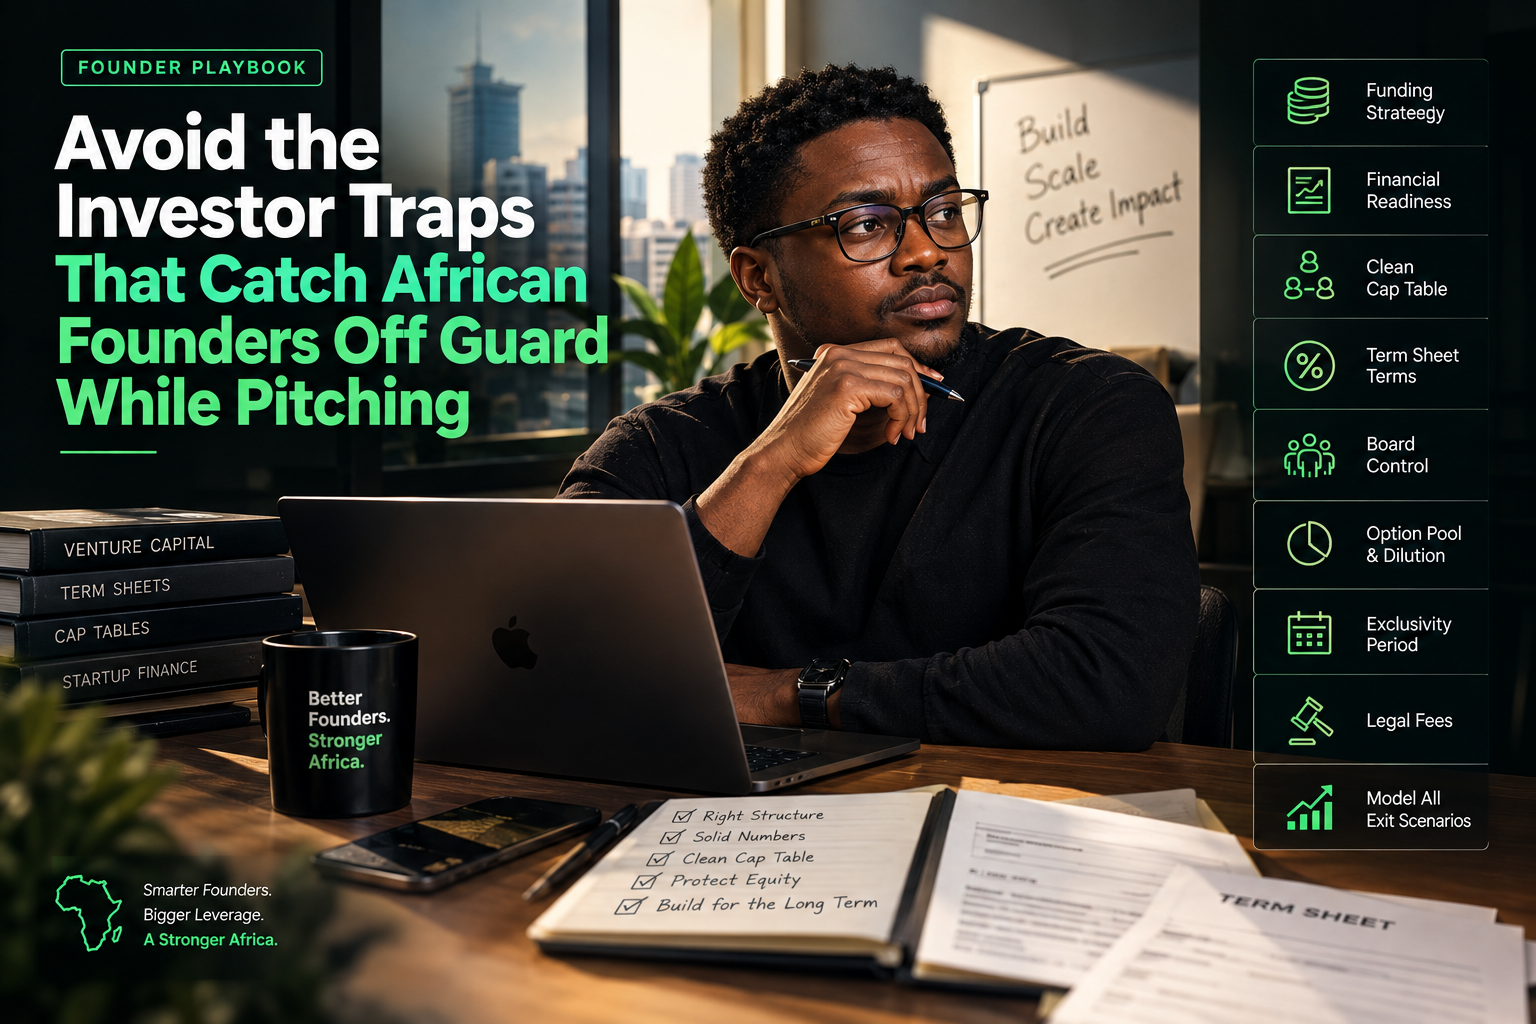
Getting an investor to say yes is not the finish line founders often treat it as. A badly structured term sheet, a fundraising strategy built for a market that no longer exists, or a cap table left messy for too long can cost a founder far more than the round itself is worth, sometimes years later, at the exact moment they can least afford it. Here’s a practical walk-through of the traps that catch African founders most often, and what to actually do about each one before you’re sitting across from an investor.
Trap One: Pitching for a Fundraising Market That No Longer Exists
The single biggest mistake many founders make walking into 2026 pitch meetings is assuming the fundraising landscape still looks like it did even a year earlier. It doesn’t. In the first quarter of 2025, equity represented nearly 89% of all capital raised by African startups. By the first quarter of 2026, debt had pulled nearly level with equity, each now accounting for roughly half of total funding raised across the continent. A founder walking into a pitch prepared only to talk about equity terms, and unprepared to make the case for why their business fits a debt or blended structure, is pitching an outdated playbook to investors who are actively thinking in a different framework. Before you build your pitch, know which structure actually fits your business model, and be ready to make that case explicitly rather than assuming equity is the only conversation on the table.
Trap Two: Showing Up Without the Financial Package Investors Now Expect
The minimum viable financial package for a serious 2026 fundraising conversation includes a three-year financial model with clearly stated assumptions, historical management accounts if you already have revenue, a genuine unit economics breakdown, and a use-of-funds statement tied specifically to the round you’re raising, not a vague growth narrative. Founders who show up without these documents aren’t just underprepared, they’re signalling to an investor that the operational discipline needed to actually deploy capital responsibly isn’t there yet either. This groundwork can’t be built during due diligence once a term sheet is already on the table. The startups that successfully closed Series A rounds through 2025 and 2026 had audited accounts, functioning board structures, and monthly management accounts already running eighteen to twenty-four months before they started fundraising in earnest, not assembled in a scramble once an investor asked for them.
Trap Three: Walking Into a Pitch With a Messy Cap Table
Investors examine cap tables carefully, and the red flags they’re watching for are specific: founders who gave away too much equity too early, messy or undocumented employee stock option arrangements, shareholders who are difficult to identify or contact, and ownership structures complicated enough to create real ambiguity around who actually controls the company. A clean, well-documented cap table isn’t just paperwork, it’s a direct signal to an investor that you understand how a fundable business is actually structured. If your cap table has problems, fix them before you start pitching, not mid-negotiation once an investor has already flagged the issue and started discounting your credibility because of it.
Trap Four: Participating Preferred Stock
Once you’re actually reviewing a term sheet, the liquidation preference clause deserves your closest attention. The clean, founder-friendly standard is a 1x non-participating liquidation preference, meaning an investor gets their initial investment back first at an exit, then steps aside while remaining proceeds get distributed proportionally. The trap is participating preferred stock, where the investor gets their money back first and then also shares in the remaining proceeds as if they were a common shareholder too, effectively double-dipping at the exact moment a successful exit should be rewarding the founders and team who built the company. This single clause can cost founders millions at exit without ever showing up as an obvious problem during the initial pitch conversation.
Trap Five: Giving Up Board Control at the Seed Stage
Never give up board control this early. A two-to-one or three-to-two founder majority on the board is the standard worth fighting for at seed stage, and conceding it under pressure to close a round quickly can hand an investor effective control over strategic decisions long before the company has proven whether that investor’s judgment is actually any better than the founders’ own.
Trap Six: The Option Pool Shuffle
This one is subtle enough that founders regularly miss it entirely. Some investors will ask for the employee option pool to be expanded before the round officially closes, which sounds like a routine housekeeping request but actually dilutes the founders disproportionately compared to the new investor, quietly lowering the effective valuation of the deal below the headline number both sides agreed to. Model exactly who ends up owning what, before and after any requested option pool expansion, before you sign anything.
Trap Seven: Open-Ended Exclusivity Periods
A no-shop or exclusivity clause, which prevents you from continuing to talk to other investors while your current one completes due diligence, is standard practice, but the length matters enormously. Aim for 30 to 45 days, and firmly resist anything longer than 60. An extended exclusivity period gives one investor outsized leverage over your company and kills your fundraising momentum entirely if that specific deal ultimately falls through, leaving you back at the start with less runway than when you began.
Trap Eight: Uncapped Legal Fees
It’s standard for a company to cover the lead investor’s reasonable legal fees as part of closing a round, but that commitment should never be open-ended. Insist on a cap, typically in the $25,000 to $50,000 range for a seed round, before you agree to cover those costs at all.
The Practical Habit That Ties All of This Together
Before signing any term sheet, model it in a spreadsheet across every plausible exit scenario, not just the optimistic one, so you can see exactly who gets what and in what order if the company sells for less than everyone hoped, not just if it becomes the next major success story. And get real legal counsel involved before your first term sheet lands in your inbox, not after, since restructuring a deal or a cap table mid-fundraise is expensive, slow, and exactly the kind of distraction a founder can least afford while trying to close a round. The founders who navigate fundraising well aren’t the ones who avoid every hard negotiation, they’re the ones who show up already knowing which fights are actually worth having.